A secured card’s limit can only change through the options the issuer allows. Do not send an extra deposit assuming it will automatically increase your available credit. Start by confirming the product’s funding and review rules.
Identify which kind of change is possible
There are three separate questions: can you add collateral, can the issuer review the existing limit, and can the account become unsecured? A “yes” to one does not establish a right to the other two.
For example, Capital One describes additional deposits within an opening funding window before activation, subject to its maximum. That is not a general permission to top up any active secured card at any time. Check your own agreement.
Know what you want the change to achieve
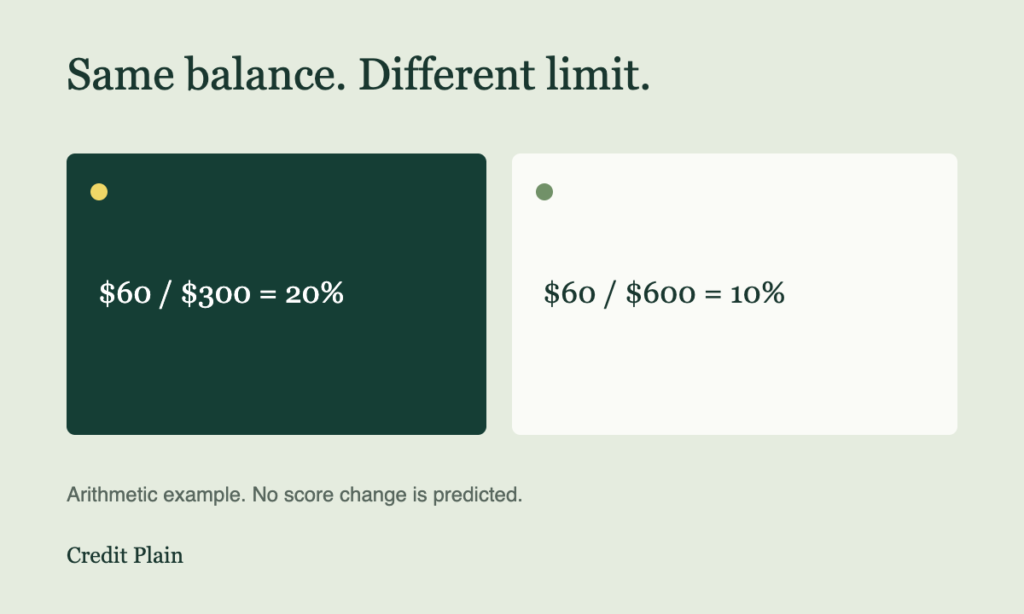
Imagine a fictional account with a $300 limit and a $60 balance. Utilization is 20%. A confirmed limit of $600 with the balance unchanged would make it 10%. But if spending also rose to $180, the new ratio would be 30%. A larger limit alone does not control the balance.
Write down the purpose of a change: supporting a necessary purchase, adjusting utilization or avoiding a very tight borrowing ceiling. Then check whether the repayment budget still works. Available credit is not income.
Use this conversation checklist
- Is a deposit increase allowed on my existing account?
- What minimum, maximum and funding deadlines apply?
- Will there be a hard inquiry or another eligibility review?
- When does the changed limit become usable?
- Do any fees or other terms change?
Verify the result
Wait for confirmation in your account rather than making a purchase against a requested limit. Keep any written notice with your agreement. If money has moved but the limit has not changed, contact the issuer through an official channel.
Use the utilization calculator to compare scenarios. It will calculate ratios, not predict whether the issuer accepts a request or how a score changes.
Sources and context
Sources checked October 23, 2026. Examples are hypothetical. This educational prototype uses AI-assisted drafting and has not received independent financial expert review.